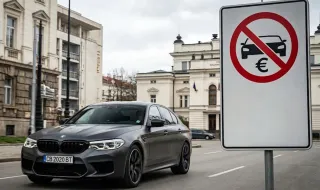
The launched ideas for introducing a new registration tax or excise tax on powerful and expensive cars upon their initial registration in our country once again raise fundamental questions about the legal competence of their importers. Under the guise of urgently filling the gaps in the budget, the government is once again demonstrating a complete lack of expertise and ignorance of automotive matters. After announcing their initial plans, in the ensuing media storm, the government quickly took insurance, announcing that electric vehicles would be excluded from the scope of the new tax. However, this does not clear up the case, but only confirms that the proposal was created by laymen, whose financial experiments threaten to bring Bulgarian legislation head-on into conflict with the legal order of the European Union.
In order to understand exactly where the trap lies, it is necessary to carefully differentiate the concepts according to EU law
In European practice, there is a clear dividing line between the concepts of customs duty and internal taxation. Any fee, the payment of which is required solely by reason of the fact of crossing the state border, is subject to an absolute prohibition under Article 30 of the Treaty on the Functioning of the European Union (TFEU), which regulates customs duties and charges having equivalent effect. However, when taxation is required upon subsequent administrative registration with the Traffic Police, the Court of Justice of the EU regards the tax as an element of the internal tax system.
However, national legislators do not have unlimited carte blanche to form these taxes at their own discretion, especially when it comes to used vehicles from so-called new imports. Here the strict framework of Article 110 TFEU comes into force, which prohibits the imposition of higher internal taxes on goods from other Member States compared to the burden borne by similar domestic products. According to the established case law of the Luxembourg court, the tax on a used car imported — say, brought from Germany — in no case can it exceed the residual amount of the same tax already included in the market value of its analogue circulating on the local market.
The main trap in the possible application of such a scheme concerns existing vehicles
Let's consider the following hypothetical example: a registration fee of 10,225 euros is set for a high-end sports model, such as the BMW M5 Competition, for example. If a brand new such car is registered after the regulation comes into force, its owner pays the full tax, which depreciates over time and remains proportionally built into its residual value. Subsequently, the import of a similar 5-year-old copy from an EU country can be legally taxed only up to the amount of this same residual burden.
The real legal absurdity arises when comparing it with cars that have already entered circulation in Bulgaria before the adoption of the new regulations. If a used sports car from 2020, which is already in the country, is sold on the secondary market without any built-in tax burden, and for a completely identical car from the same year, imported today from the EU, the state requires a full excise duty of 10,000 euros, there is direct and illegal discrimination under Article 110 of the TFEU. Such a curious mechanism artificially increases the price of the imported car, while placing the local one in a privileged position.
The legal history of our country and the region already contains enough warning signs
In case C-402/09 Tatu, the Court of Justice of the EU categorically determined that European law does not allow taxes upon initial registration, the design of which discourages the purchase of used vehicles from other member states in favor of local ones. What is more — in case C-2/09 Kalinchev, directly affecting the Bulgarian excise duty on used cars from the past, it was confirmed that the taxation of an imported used car cannot exceed the tax burden on similar vehicles already in circulation in our country.
For this reason, the key issue in the prepared legal changes is not whether our country has the right to tax powerful or luxury cars — such a sovereign possibility undoubtedly exists. However, it is critically important how exactly the regulatory methodology itself will be constructed. Any regime that imposes a full registration tax on imported used cars, without taking into account their natural depreciation and the complete lack of such a tax on the already established car fleet, will very soon be declared incompatible with European Union law.
Ultimately, such hasty ideas for new fiscal burdens once again show the lack of professional legal and automotive analysis in the state administration
Instead of looking for a working and logical mechanism for rejuvenating the aging car fleet and fair taxation based on real environmental indicators and harmful emissions, populist proposals are once again being launched that make a heavy compromise with the quality of the legislation. The cost of these reckless financial maneuvers is well known - subsequent criminal proceedings from Brussels, lawsuits from affected citizens, and again millions in compensation paid directly from the state budget at the expense of Bulgarian taxpayers.